We’re Panicking Again
Hoagie Haven in Princeton is the go to spot for a late night snack, for people in the neighborhood and the university. Back when I lived here, it stood open 24hrs per day, 7 days a week. Their special sandwich is called The Sanchez, a mix of french fries, fried chicken cutlets and their signature spicy sauce. Down the block from it is the Vara AI Fund, housed here — by babies managing $26b, down from $44b in July in a hyper focused fund.
Here is the manager.

No shade at all on being young and able to attain such a massive AUM. Congrats to him. I am sure he learned a lot at the local Blackrock down the block from his offices for the 2 years prior to founding one of the largest hedge funds in the world. If this sounds familiar to Leo at Situational Awareness — that’s because their stories are nearly identical. Both had incredible run ups and apparent busts. In July of this year when risk went off — VARA shed 44%.

Both own the same shit, as well as many other funds doing the same thing — like Lone Pine, Coatue and countless others.
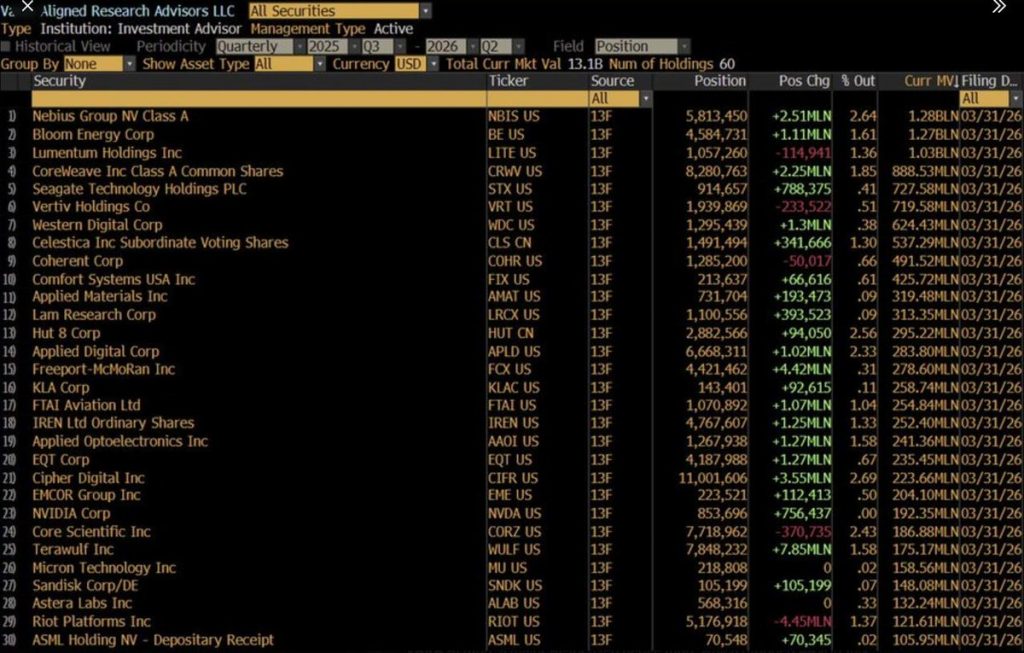
The net result of America’s vast wealth coupled with a technological revolution is massive funds chasing the same stocks — which in turn have ratcheted up the beta ratios of any stocks in this trade. This is the 7th 10% correction in SMH since last year and the 22nd 10% drawdown or more in AI fav CRDO. This combination can wreak havoc on portfolios or create massive upside opportunity, depending on exposure and timing.
This week’s rout in AI centric growth stocks stemmed from two things: CRWV debt fears + elevated inflation. All roads lead back to Tehran in this regard, since the inflation is caused by high energy prices and the rates are a response to that. When risk free rates shoot higher, so does junk and many of the neoclouds are rated junk, making their funding a concern. In spite of hotter than expected CPI numbers, rates started to come down in earnest midweek due to the belief that the enormous AI debt issuance, which has been competing with treasuries, might ease — causing many in the trade to panic sell and when they did sell they sold with alacrity in the names associated with funds like VARA, Situational Awareness, and Lone Pine.

Thus far, we haven’t heard any negative news from any of the associated companies in the AI build out trade. Both ASML and TSM reported last week, much better than expected results. Ergo, and this goes without saying, if the capital remains abundant and CRWV doesn’t all of a sudden become a going concern — this is more of a plumbing issue than structural. The chief difference between now and 2000 is demand — and it is not abating. As a point in fact, demand for compute has never been higher, unlike the dark fiber days of 2000.
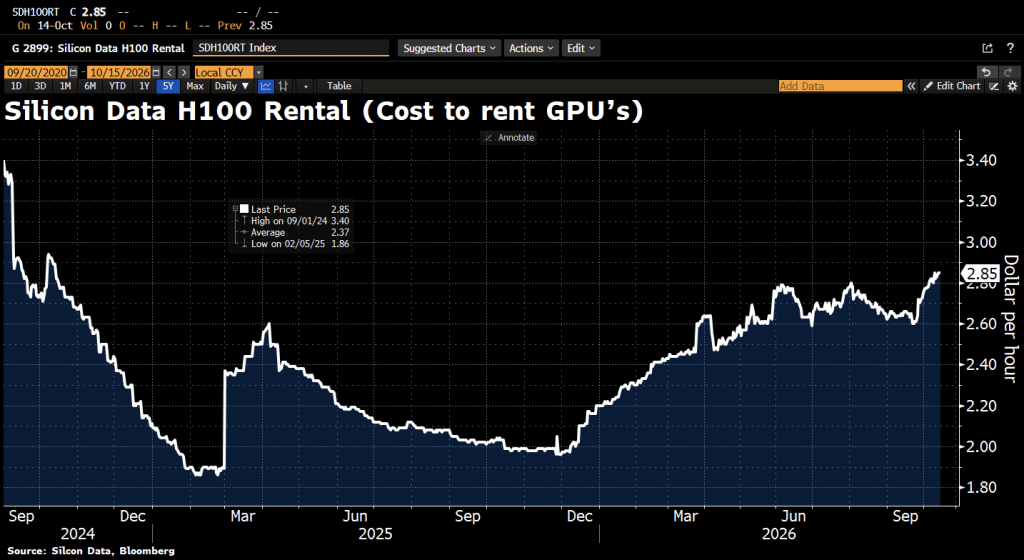
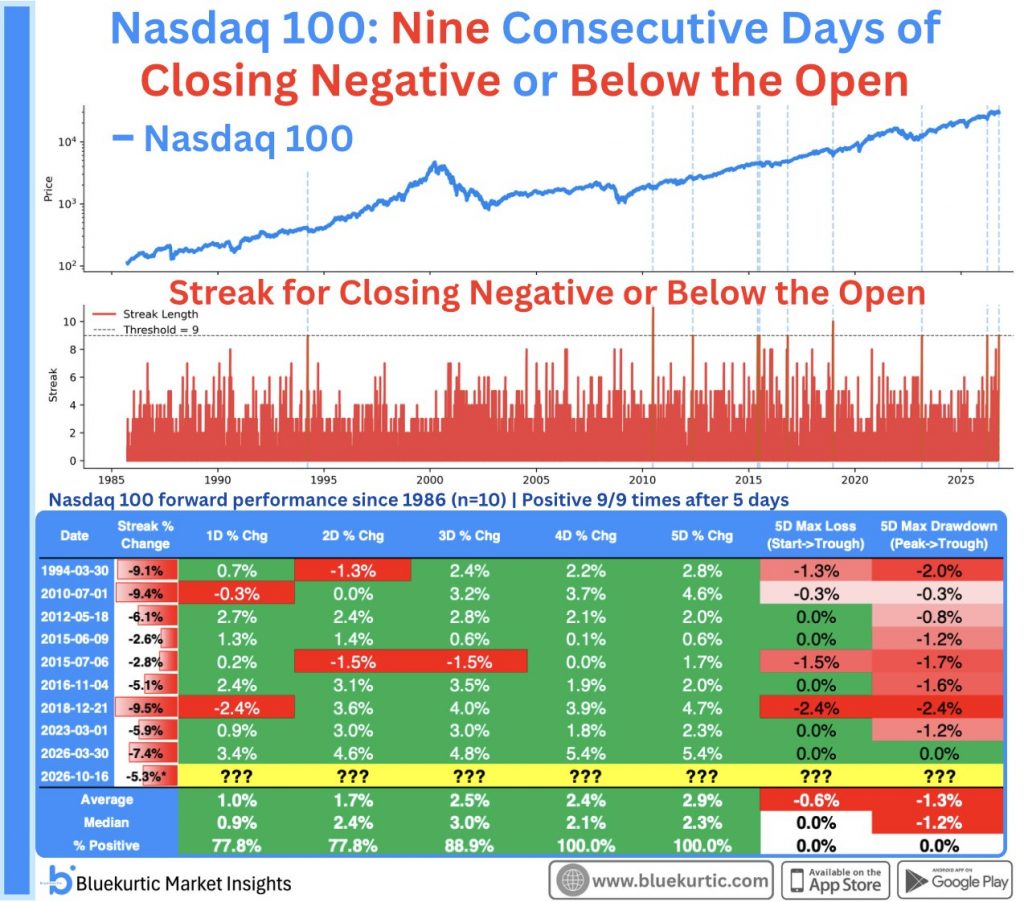
Under normal circumstances, drops like we’ve just had have led to sharp recoveries.
After all, we are heading into National Festival day and all will soon be both merry and fat, sashaying thru our local Whole Foods’ for $200 turkeys and boasting to neighbors about our stuffing and cranned berried recipes.
But at the moment, we are panicked, curious in regard to what lurks behind the bend. We read scary tales on X about CDS spreads and ponder heavily about the Anthropic IPO, where all seems to hang in the balance. Since most traders box watch and hyper obsess over every single tick, marking to market is constant and daily events exaggerated.
If you didn’t live in this era and looked back on this chart of the Q’s — you’d merely surmise the gains enjoyed from March to May had consolidated — traded sideways whilst markets dealt with the energy and rate crisis of 2026.

FAG-BOX, see above
What next?
We have earnings, the midterms, and the building crisis in shipping rates and lack of oil supplies. Nothing works in the market without cheap credit, period end of story. We can hem and haw about it and discuss various ways to skin the cat, the latest chip or the fastest fiber, the best sand — but none of this means anything if rates and oil do not come down. Alas, you have a decision to make: bet on that happening via some high beta moonshot bets like Ben Hoskin or lean into a more diversified portfolio with healthcare, maybe some COST (long), and names that aren’t owned by every hot AI fund in the world now.
As the SMH logged 9 days in a row lower, the retail ETF XRT was up 11 of 12.

You can either live your lives pivoting like a fucking moron from one rotation to the next or perhaps maintain a portfolio diversified enough to allow you to live to fight another day. The number one rule in this game is to compound returns and never bet the ranch on one hunch. Your wealth should be created via enterprise and your work, and your investments should help you to grow said wealth to outpace the scourge of inflation.
As always, see you fuckers next week.
DISCLOSURES
Based Capital Wealth LLC (“Based Capital Wealth”) is a registered investment adviser with the State of North Carolina. Registration as an investment adviser does not imply a certain level of skill or training and should not be construed as an endorsement of the firm by any regulatory authority. Based Capital Wealth only transacts business in states where it is properly registered, notice-filed, or otherwise qualifies for an exemption or exclusion from registration requirements. Additional information about Based Capital Wealth, including its current Form ADV Part 2A disclosure brochure, is available upon request.
This material is provided for informational and educational purposes only and does not constitute an offer to sell, a solicitation of an offer to buy, or a recommendation regarding any security, investment strategy, or advisory service. The views expressed herein are those of the author as of the date of publication and are subject to change without notice.
While information contained herein is believed to be reliable, Based Capital Wealth makes no representation or warranty as to its accuracy, completeness, or timeliness. The information presented should not be relied upon as a complete analysis of any security, market, industry, or investment strategy. Past performance is not indicative of future results.
This material should not be construed as legal, accounting, or tax advice. Individuals should consult with their own legal, tax, or accounting professionals regarding their specific circumstances before making any financial decisions.
All investments involve risk, including the possible loss of principal. There can be no assurance that any investment objective will be achieved or that any investment strategy will be successful.
Certain information contained herein may include forward-looking statements. Forward-looking statements can generally be identified by the use of terminology such as “may,” “will,” “should,” “expect,” “anticipate,” “project,” “estimate,” “intend,” “continue,” “believe,” or similar expressions. Actual results may differ materially from those projected or implied due to various risks, uncertainties, and market conditions. Nothing contained herein should be construed as a guarantee or assurance regarding future results.
Any hyperlinks provided are offered solely as a convenience. Based Capital Wealth does not control, endorse, or assume responsibility for the accuracy, completeness, or content of any third-party website.
Any market indexes, benchmarks, or other financial measures referenced are provided for comparative and illustrative purposes only. Indexes are unmanaged, do not incur management fees, costs, or expenses, and investors cannot invest directly in an index. Comparisons to benchmarks have limitations because benchmark characteristics may differ materially from those of a particular investment portfolio.
References to specific securities, companies, sectors, or industries are provided solely for illustrative or informational purposes and should not be considered recommendations to buy, sell, or hold any security. Such references do not represent all securities purchased, sold, or recommended for advisory clients.
The securities, investments, or strategies discussed may not be suitable for all investors. Readers should not assume that any investments identified were or will be profitable. Investment recommendations made in the future may differ materially from those discussed herein.
Asset allocation, diversification, and other portfolio management techniques do not assure a profit, guarantee against loss, or protect against market risk. Changes in market conditions, investment strategies, contributions, withdrawals, and other factors may materially affect portfolio performance. There can be no assurance that any portfolio will achieve its investment objectives or outperform any benchmark.